A weekly cash review is a short, fixed-agenda meeting in which a finance team of three checks the reconciled cash position, the expected dates that moved since last week and the low point of the 13-week forecast. The team decides what sits within its own authority and escalates the rest to the finance director with a number attached. This guide sets out what the team looks at each week, who owns each item, and what gets escalated, for a team running a connected cash flow forecast rather than rebuilding a spreadsheet.
What a weekly cash review is for
The monthly cash pack tells the board where cash stands and why. The weekly review is the routine underneath it: the point in the week where the team looks at the forecast together, corrects what the last seven days have disproved, and decides whether anything needs a decision before the next review. It is a management meeting, not a governance one. Nothing is signed off for external use. What comes out of it is a short list of actions with names against them and a forecast that is truer than it was on Monday morning.
The review is also defined by what it is not. It is not the place where the forecast gets built or the data gets reconciled; that work happens before the meeting, and a review that turns into a rebuild has failed. It is not the monthly cash reporting pack, which summarises the month for a board reader and is produced on a different rhythm. And it is not the process of setting up cash flow forecasting in the first place, which our implementation guide covers.
No professional body prescribes a weekly cash review for a business of 11 to 50 staff. ICAEW's guidance on cash flow processes for finance professionals says the frequency of cash meetings depends on the level of concern and should be weekly at minimum. CPA Australia's guide to managing liquidity risk, written with smaller businesses in mind, prepares forecasts monthly as the general case and adds a weekly view where conditions are volatile or a cash milestone needs watching. The Association of Corporate Treasurers describes the operational forecast as a rolling 13 weeks updated weekly or monthly depending on the industry and the economic circumstances. The cadence in the guidance is set by how much cash worries you, not by how many people you employ.
This page recommends weekly anyway, for one reason. The argument against a weekly review has always been cost: assembling the position from bank portals and a spreadsheet takes most of a day, so doing it every week takes most of a week. A connected forecast removes the assembly. When the reconciled balances, open invoices and unpaid bills are already in the model, the review is twenty minutes of judgement rather than a morning of data entry, and at that price weekly is cheaper than the surprises it prevents.
What the team looks at: seven items
The agenda is the same every week, in the same order. Familiarity is the point; the meeting is fast because nobody has to work out what to look at.
Reconciled opening cash. The balance the forecast starts from, per account and per entity, and when it was last reconciled. If the reconciliation is more than a few days old, that is the first item on the action list and the rest of the review is read with that caveat.
Receipts due in the window, and the expected dates that moved. Every customer receipt expected in the next 13 weeks, reviewed against the expected payment date rather than the invoice due date, with the ones whose expected date moved since last week called out. Those movements are where most of the forecast's error lives.
Payments due, including payroll, tax and debt. The committed outflows week by week: supplier bills by their agreed date, payroll on its date, VAT or sales tax on its date, loan repayments and any lease or hire purchase instalments. The team is looking for a week where several of these coincide.
The low point, and the week it falls. The lowest closing balance in the 13-week view and the date it lands on, compared with the minimum cash balance the business has set. This is the single number the finance director wants from the review.
Variance against last week's forecast. What the model said would happen in the week just gone, against what happened, by category. A variance is either timing, amount or assumption, and the team records which before it decides anything.
Overdue receivables past the agreed age. Customers whose invoices have passed the point at which the business has decided a call is made rather than a reminder sent. The age is the business's own choice; what matters is that it has been chosen in advance.
New commitments inside the window. Anything agreed since last week that will take cash out within 13 weeks: a purchase order, a hire with a start date, a contract renewal, a settlement. If it has been agreed but is not yet in the forecast, it goes in during the meeting.
Together these seven cover what has changed, what is coming, and whether the two still fit. None of them is prescribed by a professional body as a meeting item; several of the underlying disciplines are. CPA Australia's liquidity guidance asks whether actual cash flows are compared with forecasts and significant differences investigated and explained, whether there is a report identifying delays in collecting receivables, and whether the person managing cash is told promptly about changes in the amount and timing of receipts. ICAEW's guidance says cash flow reports should be reconciled to bank statements. The seven items are those disciplines arranged as an agenda.
Who owns each item
In a team of three the roles are usually a finance assistant or accounts receivable and payable owner, a finance manager or controller, and a finance director or CFO. The pattern below is generic finance practice; it does not depend on any particular tool, and it flexes when the team is shaped differently.
| Item | Owner | What they bring to the review |
|---|---|---|
| Reconciled opening cash | Finance assistant or AP/AR owner | Confirms reconciliation is current; flags any account behind |
| Receipts and expected-date changes | Finance assistant or AP/AR owner | Updates expected dates from customer conversations; lists the movers |
| Payments due | Finance assistant or AP/AR owner | Confirms the payment run, payroll and tax dates for the window |
| The low point and its week | Finance manager or controller | Reads it from the forecast; states headroom against the minimum |
| Variance against last week | Finance manager or controller | Classifies each material variance and proposes the forecast change |
| Overdue receivables | Finance manager or controller | Decides who is called this week and by whom |
| New commitments | Finance manager or controller | Adds anything agreed since last week; confirms it is in the model |
| The whole review | Finance director or CFO | Challenges the assumptions; takes the escalations; owns the decision |
Two conventions make this work. The first is that the person who prepares the forecast is not the person who signs off the position. ICAEW's guidance on controls over cash flow reporting says reports should be reviewed by someone other than the preparer, and in a team of three that separation falls naturally between the finance manager, who maintains the model, and the finance director, who reviews it. The FRC's factsheet on going concern for small companies notes that in many small businesses there may be no independent review of forward-looking cash assessments at all, which is a description of what often happens rather than an endorsement of it. A team of three has the people to do better, and the weekly review is where the separation lives.
The second is that every item has one named owner. Not the team; a person. When the expected date on a large receipt moves, one person updated it and can say why. When a variance is classified as timing rather than amount, one person made that call. In a smaller team the finance manager may carry the assistant's items as well, and in a team without a controller the finance director may take the variance review directly. The split changes; the rule that each line has a name does not.
What gets escalated, and the trigger for each
Escalation is the part of the review most teams leave to instinct, and it is the part that benefits most from being written down. The finance director does not need to hear about every movement; they need to hear about the ones that cross a line the business has drawn in advance. Five triggers cover most weeks.
Headroom falls below the minimum inside the window. The forecast low point drops beneath the minimum cash balance the business has set, in any of the 13 weeks. This is the trigger that matters most and the one the review is built around.
A receipt slips by more than one review cycle. A customer's expected payment date has moved by more than a week since the last review, or has moved for the second week running. One slip is a timing note; two is a collection problem.
A variance above the agreed share of the week's cash out. The gap between last week's forecast and what happened exceeds a percentage the team has fixed, for a single category or in total. The percentage is the business's own; what matters is that it was fixed before the week it is applied to.
Any action that means drawing a facility, delaying a supplier or moving payroll. These are not the finance team's decisions to take alone, whatever the numbers say. They go up with the numbers attached.
A customer past the agreed overdue age. The account is escalated to whoever owns the customer relationship, with the finance director copied, once the business's own threshold is passed.
No professional body publishes these triggers or the numbers behind them, and the guidance that exists points the other way: thresholds are set by each business, written down, and reviewed as the business changes. The Institute of Directors' governance principles for unlisted companies describe the mechanism as a schedule of matters reserved for the board and matters delegated to management, with attention to the financial thresholds at each level, and list the approval of borrowings above a set amount among the matters typically reserved. CPA Australia's liquidity guidance asks whether there are procedures to identify and report departures from the cash flow policy. The governance bodies, then, tell a business to decide the triggers and record them; the numbers themselves are practice, and the right ones depend on the size of the payroll, the tightness of the margins and the patience of the lender.
The escalation ladder has three rungs. Anything within the finance manager's delegated authority is decided in the room and recorded. Anything hitting a trigger goes to the finance director the same day, with the forecast open and the affected lines visible. Anything that changes what the board was told in the last pack, or that needs a facility or a covenant conversation, goes from the finance director to the board or the chair before the next scheduled meeting. Most weeks, nothing reaches the third rung. The value of the ladder is that when something does, nobody is deciding on the day how serious it is.
How to run the weekly cash review in six steps
Step 1: Refresh and reconcile before the meeting. The assistant or AP/AR owner brings the bank reconciliation current in every entity, refreshes the forecast from the accounting platform, and updates expected dates on any invoice or bill where a customer or supplier has said something new. The review starts from a model that already reflects the week; it does not do this work live.
Step 2: Walk the seven items in order. Opening cash, receipts and movers, payments due, the low point, variance, overdue receivables, new commitments. Twenty minutes is enough when nothing has happened; forty when something has. Each item's owner speaks to it; the finance director asks the questions.
Step 3: Classify every material variance before deciding anything. Timing, amount or assumption. A timing variance moves a date in the forecast. An amount variance changes a figure. An assumption variance changes how the category is forecast from now on. The classification decides which fix is right, so it comes first.
Step 4: Record each decision on the line it concerns. Why an expected date moved, why a customer was called, why a budget was changed: written as a comment against the invoice, bill or budget line, not in a message thread. Next week's review, and next month's pack, read the reasoning beside the number.
Step 5: Apply the triggers and escalate the same day. Check the low point against the minimum, the movers against the one-cycle rule, the variances against the agreed percentage, the overdue list against the agreed age. Anything that crosses a line goes to the finance director before the day ends, with the forecast open.
Step 6: Roll the forecast forward and confirm the actions. The completed week drops off, a new week 13 comes in, and the assumptions the variances disproved are updated. The meeting closes with the action list read back: each action has a name and a date, and the first item next week is whether they happened.
What the forecast tool provides and what the team decides
A connected forecasting tool holds the numbers the review reads: the reconciled opening balances synced from the accounting platform, the open invoices and bills with their expected dates, the 13-week and monthly views, the comparison of actuals with budget by category, and the consolidated position across entities. It shows those on screen when the team opens it, and it exports them when someone asks it to.
The judgement stays with the team. Which expected dates to move and why, how to classify a variance, which customer gets a call, whether a trigger has been crossed and what to do about it: none of that is generated. Nor is the review itself. No tool runs the meeting, decides what counts as material, or knows that the payroll date and the VAT date fall in the same week as a large customer's habitual late payment. The tool makes the twenty minutes possible by taking the assembly away; the twenty minutes are still the team's.
How Float fits
Float is a cash flow forecasting tool for the working pattern this page describes. It connects to Xero and QuickBooks Online through a one-way, read-only connection, with Sage Intacct on the waitlist, and imports bank accounts, transactions, invoices and bills every 24 hours, with a manual refresh whenever the team wants the latest position before the review.
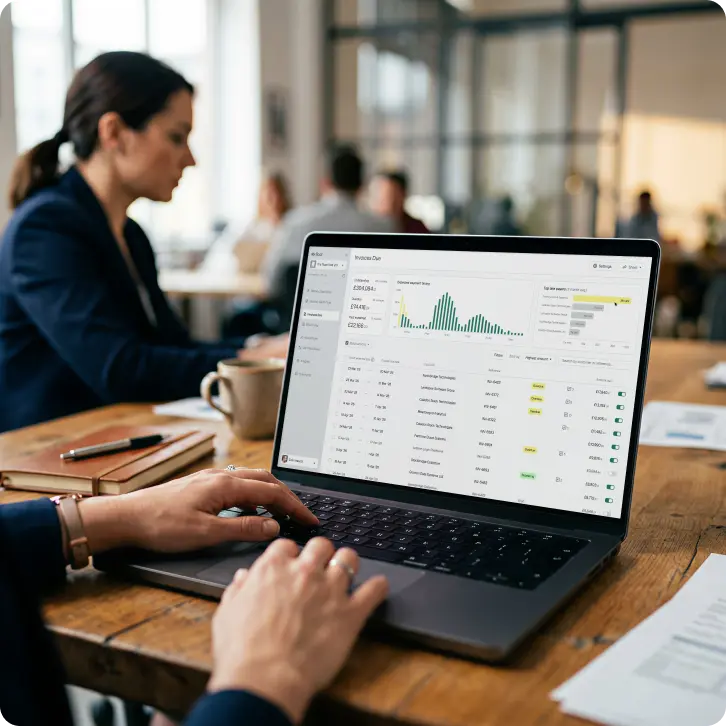
The seven items map onto what Float shows. The forecast opens on the reconciled position and runs in weekly and monthly views, so the 13-week low point and the week it falls are read from the graph. Expected payment dates can be set on any invoice or bill without touching the accounting records, which is where the receipts item and the one-cycle trigger are worked. Comments can be added directly to invoices, bills and budgets, so the record of why a date moved or a customer was called sits on the line, which is Step 4. The Insights view carries a budget variance comparison by category for the previous month or the last three months, with the accounts furthest from budget surfaced separately, which is the starting point for the variance item. Scenarios sit as named layers against the base forecast, so a what-if raised in the review can be modelled without disturbing the plan.
Ownership is set through Float's four user roles: owner, admin, editor and viewer. The finance manager maintains the model as an admin or editor; the finance director and the CEO see the same live forecast read-only. When the review needs something on paper, or the finance director wants the position sent up, the team exports the view or a report itself, on the day. Float does not schedule reports, send them, or raise alerts; the review, the triggers and the escalation are the team's process, and Float is the model the process runs on.
Frequently asked questions
How often should a finance team review its cash flow?
Weekly, for a finance team of three running a connected forecast; it is also the minimum ICAEW's guidance sets when cash is a concern. No professional body ties the cadence to headcount: CPA Australia's small-business liquidity guidance defaults to monthly with a weekly view added in volatile conditions, and the Association of Corporate Treasurers describes weekly or monthly updates depending on circumstances. A connected forecast makes the review cheap enough to justify every week.
What should a weekly cash review look at?
Seven items, in the same order every week: the reconciled opening cash, the receipts due in the window and the expected dates that moved, the payments due including payroll, tax and debt, the forecast low point and the week it falls, the variance against last week's forecast, the receivables past the agreed overdue age, and any new commitments agreed since last week. The list is working practice rather than a published standard; the disciplines behind it, such as comparing actuals with forecast, appear in professional-body guidance.
Who should own the weekly cash review in a small finance team?
The finance manager or controller owns the model and the review's preparation; the finance director or CFO chairs the review, challenges the assumptions and takes the escalations; the finance assistant or AP/AR owner brings the reconciliation and the expected-date updates. ICAEW's guidance says cash flow reports should be reviewed by someone other than the preparer, and in a team of three that split falls between the finance manager and the finance director.
What should be escalated to the finance director?
Five triggers cover most weeks: the forecast low point falling below the minimum cash balance inside the 13-week window, a customer receipt slipping by more than one review cycle, a variance above the percentage the team has agreed, any action that would mean drawing a facility, delaying a supplier or moving payroll, and any customer past the agreed overdue age. The numbers are set by each business and written down; governance guidance for unlisted companies describes the mechanism as a schedule of reserved and delegated matters with financial thresholds at each level.
How long should a weekly cash review take?
Twenty minutes in a normal week and up to forty when something has moved, provided the reconciliation and the refresh were done beforehand. No professional body prescribes a length; the figure is practice. A review that regularly runs longer is usually doing preparation that belongs before the meeting.
What is a minimum cash balance, and how is it set?
A minimum cash balance is the floor the business has decided it will not plan below, and the weekly review compares the forecast low point against it. CPA Australia's liquidity guidance describes a minimum liquidity buffer as a policy the business sets itself, expressed as a stated amount, a share of committed facilities or a value of liquid assets, and justified by a stated method such as a number of months of operating cash flow. No professional body recommends a level; it comes from the business's own history of fluctuations.
Should receipts be reviewed against due dates or expected dates?
Expected dates. An invoice's due date is the term the customer agreed to; the expected date is when the money is likely to arrive, based on how that customer has actually paid. UK government statistics for 2025 show large businesses paid 15% of invoices later than their agreed terms, with the average time to pay unchanged at 32 days since 2023, and Australia's Payment Times Reporting Regulator found 68.5% of invoices from reporting entities paid within terms in the second half of 2025. A forecast built on due dates alone is wrong on roughly one large-customer receipt in seven, in a predictable direction.
How does the weekly review relate to the monthly cash pack?
The monthly pack is the summary of decisions the weekly reviews have already taken. The comments recorded against invoices, bills and budgets during the month become the variance narrative; the escalations that reached the finance director become the decisions section; the forecast the board sees is the one the weekly reviews have been correcting. Run the weekly review well and the pack is mostly assembled by month end. Our guide to the monthly cash reporting pack covers that side.
Can cash flow forecasting software run the weekly review for us?
No, and it should not. Software provides the numbers the review reads: the reconciled position, the forward views, the variance comparison, the expected dates. The review is judgement: what a variance means, which customer to call, whether a trigger has been crossed. Float shows the model and exports what the team asks for; it does not schedule reports, distribute them or raise alerts. The meeting, the triggers and the escalation ladder are the team's.
Who should be able to see the forecast the review uses?
The people who maintain it need edit access; everyone else should see it read-only. In Float that means the finance manager or controller as an admin or editor, with the finance director, the CEO and any budget holders as viewers of the same live model. Two-factor authentication is mandatory for customers connecting to Xero and recommended for everyone else, and access is set per person when they are invited.
How much does cash flow forecasting software for a small finance team cost?
Connected forecasting tools are priced as monthly subscriptions alongside the accounting platform they connect to. Float's current plans and a free trial are on our pricing page.
If your weekly cash review still starts with someone rebuilding the position from bank portals and a spreadsheet, the fastest way to see what twenty minutes looks like is with your own numbers. Start a free trial and Float will build the forecast your first review reads directly from your Xero or QuickBooks Online data.