Moving from an annual budget to a rolling cash forecast means keeping the budget as the fixed plan for the year and running a separate forecast of cash, by month, that you re-baseline on actual results every month and extend by one month each time, so it always looks the same distance ahead. The budget stays where it was set; the forecast moves with what has happened. For a finance team of three, the change is a monthly routine, not a new system.
This page covers what the annual budget is for, why it stops describing cash within a month or two of the year starting, what a rolling cash forecast is, how to make the change step by step, who owns each part of it, and what to do with the original budget once the forecast is running. It does not cover the weekly cash review, the monthly reporting pack or the 13-week template, which have their own pages.
What the annual budget is for
An annual budget is the plan for the year, in numbers. Professional guidance describes it as the quantitative expression of a plan for a defined period, used to set the level of income and spending, authorise that spending, and give managers something to be held to. Three jobs follow from that: it allocates resources, it sets targets, and it is the yardstick for control, because performance is measured against it.
Those jobs need the number to stay still. A target that moves every month is not a target, and spending authorised against a plan that keeps changing is hard to control. That is why professional-body guidance treats the budget as fixed for its period, and why it treats a forecast as a different document: the budget says what you set out to do, the forecast says what you now expect to happen.
Most annual budgets are profit and loss budgets. CPA Australia's guidance puts it plainly: most businesses will prepare an annual profit and loss budget, and although the annual budget is the basis on which the cash flow forecast is prepared, cash should not be confused with profit. That sentence is the whole reason this page exists.
Why the budget stops describing cash by month two
A profit and loss budget records income when it is earned and costs when they are incurred. Cash moves on different dates, and some cash never appears in the profit and loss at all. Within a month or two of the year starting, four gaps open between the budget and the bank balance.
The first is timing. The budget books March sales in March. The customer pays in May. Under UK payment-practices reporting, large businesses paid their suppliers in a median of 32 days in 2025 and paid 15% of invoices late by number and 14% by value, according to the Department for Business and Trade's Official Statistics released in July 2026, based on 11,178 reports from businesses above the large-company thresholds. In Australia, the Payment Times Reporting Regulator's August 2026 update put the average payment time by reporting entities to their small business suppliers at 27.2 days, with 68.5% of invoices paid on time. Both figures describe how large payers behave, which is exactly what matters if your customers are large. They say nothing about how businesses of your size pay, and nothing on this page assumes they do.
The second is the cash that a profit and loss budget does not carry. A cash forecast has rows the budget does not: VAT or GST payments and refunds, tax payments, capital expenditure, loan repayments, and drawings or dividends. CPA Australia's checklist for a cash budget asks whether it includes capital expenditure, acquisitions, tax payments, drawings, dividends or investments. None of those is a line in a profit and loss budget, and every one of them is a date on which cash leaves.
The third is the statutory calendar. The dates are fixed and knowable, and they fall where the profit and loss budget cannot see them. In the UK, a quarterly VAT return and its payment are due one calendar month and seven days after the period ends; PAYE and Class 1 National Insurance reach HMRC by the 22nd of the following month if paid electronically; employee pension contributions reach the scheme by the 22nd of the month after deduction; corporation tax is due nine months and one day after the accounting period ends where taxable profits are under £1.5 million. In Australia, the quarterly BAS is due on the 28th of the month after the quarter, with the December quarter due 28 February. In New Zealand, GST is due on the 28th of the month after the taxable period, except the period to 31 March, due 7 May, and the period to 30 November, due 15 January. In the US, sales tax filing dates are set state by state, on the state's own frequency.
The fourth is that the budget is fixed by design. It was built in October or November on assumptions about prices, headcount and customers. By February some of those assumptions have already been overtaken. The budget cannot absorb that, and should not. Something else has to.
What a rolling cash forecast is
A rolling forecast is one that always extends a set number of periods into the future. ICAEW's guide to rolling forecasts describes the roll in three moves: the horizon is extended so the number of periods stays the same, figures are entered for the new period at the horizon, and all the figures already in place are updated. CIMA's terminology defines the same mechanism: a further period is added when the earliest period has expired, and each time actual results are reported the intermediate periods are updated too.
A rolling cash forecast applies that mechanism to cash rather than profit. It starts from the reconciled bank balance, schedules every receipt and payment in the month the cash will actually move, and closes each month with a bank balance. When the month ends, the forecast for that month is replaced by what happened, the assumptions for the months ahead are corrected, and a new month is added at the far end.
Two design choices follow. The horizon: twelve months is the common length for a monthly cash forecast, and it sits alongside a 13-week weekly view for the near term, which is where payroll dates and tax dates are managed. The cadence: ICAEW describes the roll as typically monthly or quarterly. This guide recommends monthly, because the statutory dates above land monthly and quarterly, and a quarterly roll would put a VAT payment on the far side of the horizon before the forecast had been corrected for it.
What the rolling forecast is not: it is not a replacement for the budget. ICAEW's guide describes finance directors implementing rolling forecasts alongside traditional budgeting, and that is the arrangement this page describes.
How to move from the annual budget to a rolling cash forecast
The change is a one-off setup followed by a monthly routine. If the budget already exists by account, the setup is a matter of moving figures to the right dates and adding the rows the budget does not carry.
Step 1: Take the annual budget's assumptions as the opening forecast, by account. For each income and cost account, the budget already says how much and, in outline, when. Copy those into the forecast as monthly expectations: recurring costs on their monthly amount, seasonal income in the months the budget puts it, one-off items in the month they were planned. Do not adjust anything yet. The point of starting from the budget is that month one's variance tells you how far the budget was from cash before you touched it.
Step 2: Move every receipt and payment to the date the cash will move. Sales income goes into the month the customer will pay, not the month the invoice is raised, using each customer's own payment pattern where you know it and the terms where you do not. Supplier costs go into the month your payment run will pay them. This is the step that turns a profit and loss number into a cash number, and it is where most of the difference between the budget and the bank balance comes from.
Step 3: Add the rows the budget does not carry, on their statutory dates. VAT or GST on its return date, PAYE and National Insurance and pension contributions on the 22nd, corporation tax nine months and one day after the year end, loan repayments on the lender's schedule, capital expenditure in the month the invoice is paid, drawings or dividends when they are declared and paid. Each gets its own row so a miss can be traced to a line.
Step 4: Set a cash floor and read the low point. Decide the balance the business must not fall below, usually the next payroll and tax run plus a margin, and find the month where the forecast comes closest to it. That month, not the year-end balance, is the number the forecast exists to show.
Step 5: At month end, replace the forecast with actuals and re-baseline the months ahead. Record what was actually received and paid against what was forecast, keeping receipts and payments apart so a miss on one side cannot hide a miss on the other. Then correct the months ahead for what the variance taught you: a customer who paid three weeks late will probably pay the next invoice late too; a cost that came in higher will stay higher. The original budget does not change. Business Queensland's guidance states it in five words: your original budgets do not change.
Step 6: Add the new month at the horizon and roll. Enter the new month's expectations at the far end, from the budget where it still applies and from the corrected assumptions where it does not. The forecast now looks the same distance ahead as it did last month, built on one more month of fact.
A month's re-baseline, worked through
This example is illustrative. The figures are invented for a services business with 30 staff, and the mechanics are the point.
The budget for April put sales income at £310,000, booked in April. The forecast, after step 2, put £140,000 of that cash in April and £170,000 in May, because the two largest customers pay at 45 days. The cash floor is £60,000. April closes. Actual receipts were £118,000: one customer paid as expected, the other paid £22,000 short, confirmed £12,000 for the second week of May and the balance for June. Supplier payments were £2,500 under because one bill missed the last payment run and moves to May.
| Line | April budget | April forecast | April actual | Variance to forecast | May forecast, re-baselined |
|---|---|---|---|---|---|
| Opening cash | n/a | £340,000 | £340,000 | nil | £201,500 (was £221,000) |
| Sales receipts | £310,000 | £140,000 | £118,000 | £22,000 under | £182,000 (was £170,000) |
| Supplier payments | £96,000 | £94,000 | £91,500 | £2,500 under | £96,500 (was £94,000) |
| Net pay | £108,000 | £108,000 | £108,000 | nil | £108,000 |
| PAYE, NIC and pension | not in budget | £57,000 | £57,000 | nil | £57,000 |
| VAT payment | not in budget | £0 | £0 | nil | £68,300 (quarter to 31 March, due 7 May) |
| Closing cash | n/a | £221,000 | £201,500 | £19,500 under | £53,700 (was £63,700) |
Three things happen in the re-baseline. £12,000 of the late receipt moves into May and £10,000 into June, so May's receipts rise but not by the full shortfall. The £2,500 of supplier payments not made in April moves into May too. And the VAT payment, which was always going to fall on 7 May, now sits in a May that opens £19,500 lower than planned, so the May closing balance drops from £63,700 to £53,700. The April budget still says £310,000 of sales, which is correct as a profit figure and is what the variance report compares against. Nothing in the budget was edited.
The number the finance director needs is not the April variance. It is that May now closes £10,000 lower than last month's forecast said, and that where last month's forecast cleared the £60,000 floor by £3,700, this month's sits £6,300 below it, with three weeks to bring the June receipt forward or move a payment back.
Who owns each step
No professional body prescribes which role in a finance team owns the budget, the forecast inputs or the monthly re-baseline. What the guidance does set are principles: responsibilities for cash matters clearly understood, and reports reviewed by someone other than the preparer, with the preparer and reviewer identified. ICAEW's principles for finance professionals managing cash put it exactly that way. The split below is this guide's recommendation for a team of three, not a standard.
The management accountant or finance manager owns the forecast: steps 1 to 3 at setup, and the month-end replacement and re-baseline in step 5. They know which customer pays late and which supplier will wait.
The bookkeeper or assistant accountant owns the inputs the forecast depends on: reconciliation is complete before the month is closed, invoices and bills carry expected dates, and the statutory calendar is loaded for the year ahead. A forecast re-baselined on an unreconciled ledger is re-baselined on a guess.
The finance director owns the floor, the reading and the sign-off: the cash floor is set and reviewed, the low month is read at each roll, and the re-baselined forecast is reviewed before it goes to anyone else. The budget stays the finance director's document too; if the business decides to re-cut it mid-year, that is a separate decision, made once, not a by-product of the monthly roll.
What happens to the annual budget
It stays. The forecast does not replace it, and the two are compared every month, which is the point of keeping the budget fixed.
There is a well-known argument for going further. Hope and Fraser's book Beyond Budgeting (Harvard Business School Press, 2003) argued that budgeting as most corporations practise it should be abolished, and the organisation that carries the idea has since said its model should not be reduced to a rolling forecasting exercise. The professional bodies did not adopt the abolition. When Libby and Lindsay surveyed 558 finance professionals in North American organisations of at least 100 employees, published in Management Accounting Research in 2010, 94% of those using budgets for control were not planning to abandon them, and the median time managers spent on budgeting was three to four weeks a year, about six to eight per cent of their time. No comparable survey exists for businesses of 11 to 50 staff, so nothing here claims what smaller businesses do.
For a business of this size, the practical position is the one ICAEW describes: the rolling forecast runs alongside the budget. The budget answers "what did we set out to do", the forecast answers "what will the bank balance be in each of the next twelve months", and the variance between them is where the finance team learns which assumptions to fix.
How Float fits
Float is a cash flow forecasting tool that runs the rolling cash forecast described above from your accounting data. It connects to Xero or QuickBooks Online through a one-way connection, imports your bank balances, invoices, bills and reconciled transactions once a day at an hour you choose, with a manual sync on demand, and offers both a monthly view and a 13-week weekly view using the direct method.
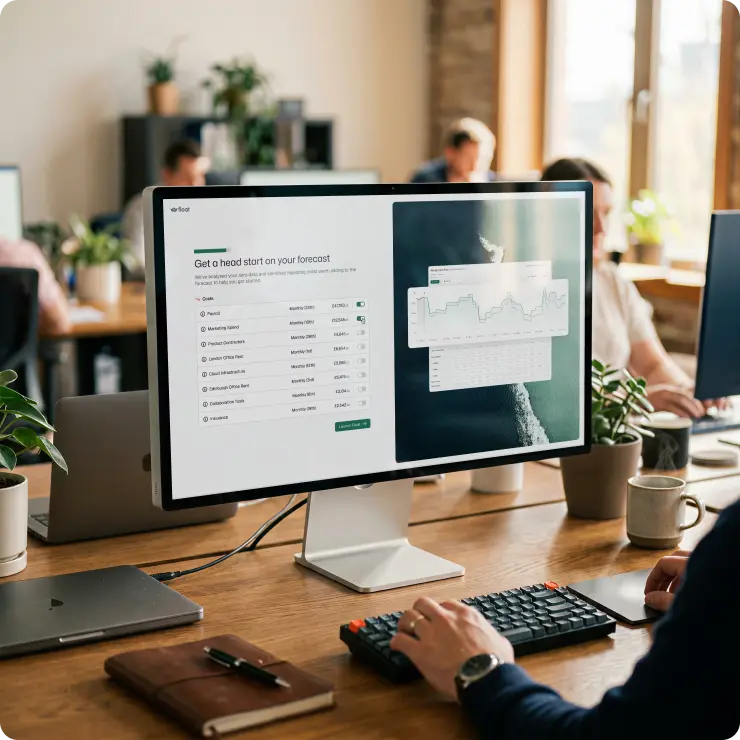
The annual budget's assumptions become budgets in Float, which the help centre describes as placeholders for cash that might come into or leave the business. A budget can be a fixed value, last month's actual or the average of the last three months; it can be set to repeat weekly, fortnightly, monthly, quarterly or annually; and it can be an auto budget that tracks the last month or the three- or six-month average of your reconciled history and updates itself as each month closes, which cannot be manually adjusted. Linked budgets set one line as a percentage of another, with a date offset for costs that follow sales. Where the budget lives in a spreadsheet, the Spreadsheet Data tool lets you paste rows of monthly figures straight into the forecast; there is no file upload, and Float does not import Xero's own budget.
The re-baseline is Float's core mechanic. Each day it pulls in the latest actuals, which in Float means the invoices, bills and bank transactions synced from your accounting platform, including invoices and bills that are still unpaid. Those actuals fill the budget placeholders as they arrive; once an actual exceeds the budget for a cell, Float uses the actual instead, and at the end of the current month all actuals replace budgets. The budget you set is still there to compare against: the Budget Variance insight shows where you were over or under budget for the last month or the last three months, and the single account view shows why for any one line.
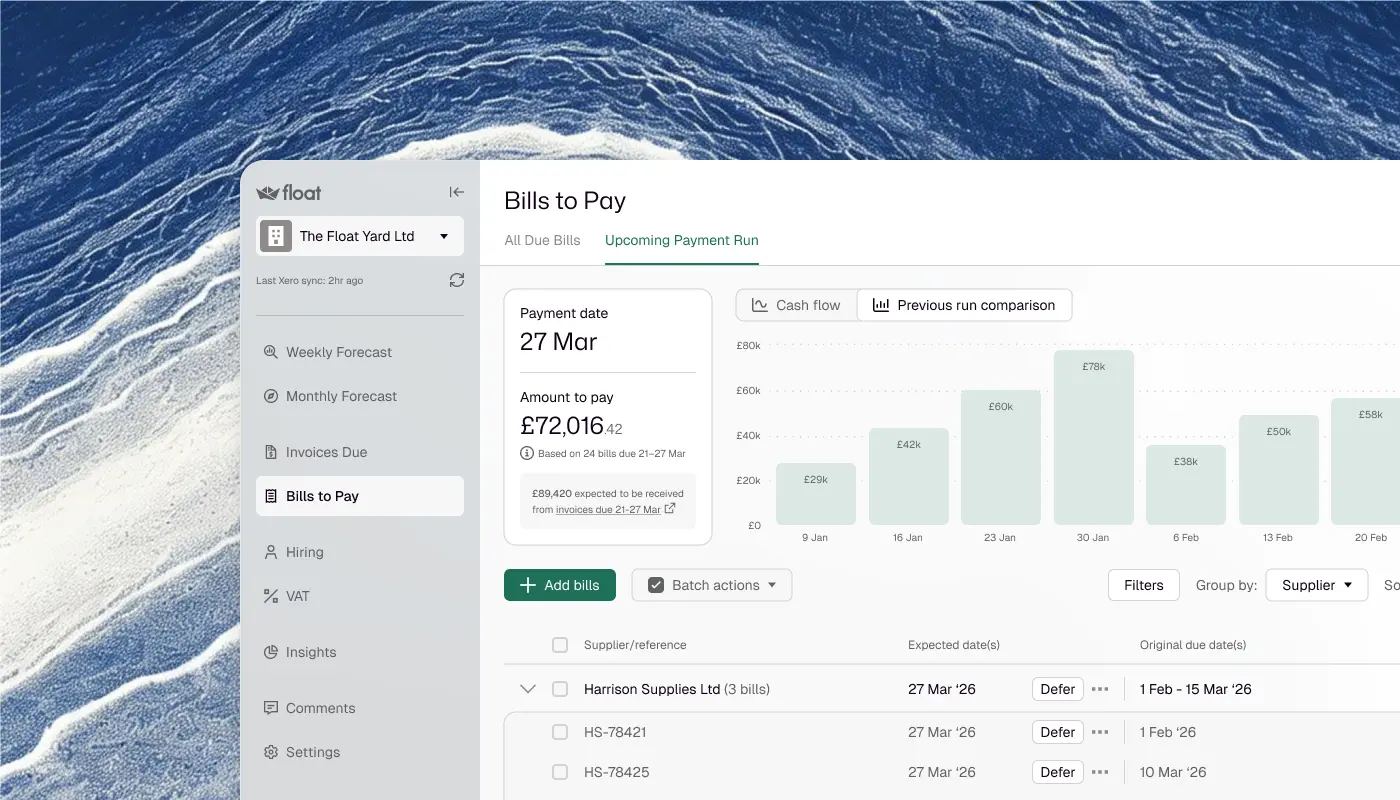
Expected payment dates do step 2. Every invoice and bill carries the date you expect the cash to move, taken from your accounting platform where one is set and otherwise the due date, and you can change it, move it forward by 7 or 30 days, split an invoice into part payments, or set expected dates in bulk. For Xero users, Smart Expected Dates applies each customer's and supplier's average lateness to new invoices and bills automatically; this is available for Xero users only. The cash floor is a threshold: set one and Float shows the date the balance is due to cross it. Scenarios stack on the base forecast, so the version where the late customer pays in June rather than May is one layer, not a second file; every plan includes a set allowance of them, listed on our pricing page. The forecast exports as a PDF or CSV whenever you want it; nothing is sent on a schedule.
Frequently asked questions
What is the difference between a budget and a rolling forecast?
A budget is the plan for a fixed period, set before the period starts and held still so that performance can be measured against it and spending controlled by it. A rolling forecast is the current expectation of what will happen, updated as actual results arrive and extended by one period each time one closes, so it always covers the same span ahead. Professional guidance treats them as different documents with different jobs, and places rolling forecasts alongside the budget rather than in its place.
How often should a rolling cash forecast be updated?
Monthly, in this guide's method: replace the closed month with actuals, correct the months ahead, add a new month at the horizon. ICAEW describes the roll as typically monthly or quarterly, and Business Queensland's small-business guidance says to review results at the end of each month against the budget and forecast. A quarterly roll leaves statutory payments such as VAT uncorrected for too long; a weekly cadence belongs to the 13-week forecast, not the monthly one.
Should the annual budget change when the forecast is re-baselined?
No. The original budget stays as set, and the re-baselined forecast is compared against it each month. Business Queensland's guidance for small businesses states it directly: your original budgets do not change. If the business decides to re-cut the budget mid-year, that is a separate decision taken once, not something the monthly roll does.
Why does a profit and loss budget not show the cash position?
Because it records income when earned and costs when incurred, and cash moves on different dates. It also carries no line for VAT or GST payments, tax payments, capital expenditure, loan repayments or dividends, each of which is a date cash leaves the bank. CPA Australia's guidance notes that although the annual budget is the basis on which the cash flow forecast is prepared, cash should not be confused with profit.
What horizon should a rolling cash forecast use?
Twelve months is the common horizon for a monthly cash forecast, long enough to see the next VAT quarter, the corporation tax date and the annual renewals, and to plan a hire or a purchase against them. It runs alongside a 13-week weekly view for the near term, where payroll and payment-run timing are managed week by week.
Who should own the rolling forecast in a small finance team?
No professional body prescribes a role map. ICAEW's principles ask that responsibilities for cash matters are clearly understood and that reports are reviewed by someone other than the preparer. In a team of three, this guide recommends the management accountant or finance manager owns the forecast and its monthly re-baseline, the bookkeeper owns reconciliation, expected dates and the statutory calendar, and the finance director owns the cash floor, the reading of the low month and the sign-off.
Does moving to a rolling forecast mean abandoning the budget?
No. The argument for abolishing budgets exists, most notably in Hope and Fraser's Beyond Budgeting (2003), but the professional bodies did not adopt it, and in Libby and Lindsay's 2010 survey of North American organisations with at least 100 employees, 94% of those using budgets for control had no plan to abandon them. The practical position for a business of 11 to 50 staff is the one ICAEW describes: the rolling forecast runs alongside the budget.
Can I import my annual budget into Float?
Not as a file. Budgets in Float are entered directly against each account, as a fixed value, last month's actual or the average of the last three months, or pasted in as rows of monthly figures through the Spreadsheet Data tool. Float does not import Xero's own budget. Invoices, bills and bank balances arrive from your accounting platform automatically; the budget assumptions are yours to enter, and the forecast fills them with actuals as the month runs.
How does Float handle the month-end re-baseline?
Automatically, from the ledger. Float imports actuals once a day; as invoices, bills and transactions arrive they fill the budget for that account, and at the end of the current month all actuals replace budgets. The budget you set is kept for comparison, and the Budget Variance insight shows where the last month or last three months ran over or under. Expected payment dates carry the timing corrections into the months ahead, and for Xero users Smart Expected Dates applies each customer's average lateness to new invoices.
Who can see the forecast in Float?
Float has four user roles: Owner, Admin, Editor and Viewer. The finance team keeps edit rights, the finance director or board can be given read-only access, and the connection to your accounting platform is one-way, so nothing done in Float changes the books. Two-factor authentication is mandatory for customers connecting Float to Xero.
The budget tells you what you planned. A rolling cash forecast tells you what the bank balance will be in each of the next twelve months, corrected every month by what has happened. Connect Xero or QuickBooks Online to Float and the invoices, bills and balances arrive on their own; the budget assumptions are yours to set, with a 14-day free trial and about three minutes to the first sync.