How do you keep a cash forecast right when a customer pays three weeks late and a hire moves by a month? You update it in four ways every week instead of rebuilding it every month. Actuals replace estimates as they land, expected dates move when a payment slips, plan changes go in as budget changes on the dates they hit cash, and one weekly review reads what moved. A month-end rebuild does the same work later, and the forecast is wrong for most of the weeks in between.
This guide is for the finance manager or controller who owns the forecast in a finance team of three to eight, and for the finance director who has to rely on it.
A forecast is not a report. A report describes a date that has passed and is finished when it is sent. A forecast describes dates that have not arrived, and every one of them can move. A forecast the team rebuilds at intervals is right on the day it is built and drifts from the next morning. A forecast the team keeps current is corrected in the week the news arrives, and the finance director reads the forecast that exists, not the one that existed three weeks ago.
Why Does A Cash Forecast Go Stale Between Builds?
A cash forecast goes stale because most of its dates are expectations rather than facts. An invoice carries a due date in the ledger; the day the money arrives is a separate question. Each time a customer pays late, a supplier moves or a plan changes, a week's closing balance moves with it.
ICAEW's cash flow principles describe that uncertainty widening the further a forecast looks ahead. The drift comes from three places.
Customers paying after the due date. The largest receipts in a forecast are usually a handful of invoices, and each customer has its own payment run. In the UK, the typical large business reported paying 15% of its invoices after the agreed terms in 2025, according to the Department for Business and Trade's payment practices statistics. In Australia, large businesses set an average payment term of 29 days to their small suppliers, and the average 95th-percentile payment time was 55 days in the second half of 2025, according to the Payment Times Reporting Regulator. Why customers pay late, and what the law lets you charge, is the subject of our guide to payment terms and late payment. This page covers what happens to the forecast when they do.
Suppliers and payroll moving. A supplier brings a payment forward. A bill approved late lands in a week the forecast had not planned for. Payroll leaves on a fixed day, and the employer taxes and pension contributions that follow it leave on statutory dates in another week.
Plans changing. A hire is confirmed, or moved. A purchase is cancelled. A price rise is agreed from next quarter. None of these reaches the ledger until an invoice or a bill exists, and by then the cash effect is weeks away from the decision.
Several bank accounts, entities or currencies add to the drift. Each account has its own receipts and payment run, and a change in one entity does not reach the group view until it is carried across. Keeping that view current is one of the weekly jobs of the operational cash layer.
The Common Way, And What It Costs
Most finance teams of this size keep the forecast current in one of two ways. They rebuild it at month-end from the ledger, or they patch a spreadsheet by hand each week until the file no longer matches anything the team trusts. Both work for a while, and both cost more than they appear to.
The month-end rebuild produces a forecast the team believes in, for a day. From the second day the dates move, and nothing catches them until the next rebuild. If the forecast was built on the 1st, the question the chief executive asks on the 15th is answered with figures two weeks old, and the weekly cash meeting discusses what has probably changed instead of reading what has.
The hand-patched spreadsheet goes the other way. One person edits cells as news arrives, which is the right instinct applied to the wrong instrument. After a few weeks the file carries overwritten formulae and a version on the shared drive that is not the one in use, and the forecast is current only when its owner is at their desk. ICAEW's principles ask that responsibilities and staff cover for cash matters are clearly understood, which a one-person spreadsheet fails. The rebuild costs time. The patched spreadsheet costs trust.
Neither is a failure of the forecast's design. A 13-week forecast is built to roll, and our guide to the 13-week cash flow forecast shows how to build one. The failure is in how it is kept between builds.
How To Keep A Cash Flow Forecast Up To Date Each Week
Keeping a cash flow forecast up to date comes down to four things the team does every week, and together they replace the rebuild. Each takes minutes if it is done in the week the news arrives, and each is a job one named person can own. Done well, most of the first three happen on their own, and the team's time goes on the exceptions.
Step 1: Let actuals replace estimates. A forecast carries two kinds of number: what the ledger knows, such as reconciled transactions, invoices raised and bills approved, and what the team expects, such as a budget for sales not yet invoiced. As the month runs, the first kind arrives and takes the place of the second, line by line, in the week it happens. The actual replaces the budget rather than sitting beside it, so nothing is counted twice. A forecast connected to the ledger makes this change every day. What the ledger supplies, and what it cannot, is set out in our guide to what a Xero ledger gives your cash flow forecast.
Step 2: Move expected dates, not due dates. The due date is the contract. The expected date is the forecast. When a customer says the invoice due on the 30th will be paid on the 20th of next month, the due date stays where it is for credit control and the expected date moves to the 20th, so the forecast shows the receipt in the week it will arrive and the gap in the week it will not. ICAEW's cash flow principles put it the same way: assign an expected date, with best- and worst-case dates, to each material receipt and payment. The best starting point for an expected date is how that customer has actually paid before, and no overdue invoice should sit on today's date by default.
Step 3: Enter plan changes as budget changes. A confirmed hire goes in as budgets for net pay on payday and employer costs on their statutory dates. A cancelled purchase comes out. A new contract goes in as expected receipts on the dates the customer will pay, not the invoice dates. A price change edits the repeating budget from the month it applies. Our rule is that the test is whether something has been decided: a decision goes into the base forecast, and a possibility stays in a scenario until it is decided. ICAEW's principles ask for worst-case, most-likely and best-case scenarios alongside the forecast, and this is where they live.
Step 4: Hold one weekly review of what moved. Not a rebuild. A look at the lines that changed since last week and the weeks that are now tight. The review reads three things: which expected dates moved and by how much, which budgets were added, removed or re-dated, and where the low point now falls against the floor the business has set. Keep last week's forecast, because the review compares against it. The agenda, who owns each item and what gets escalated are in our guide to the weekly cash review.
Together, these four steps are what CIMA's terminology describes as a rolling forecast: each time actual results are reported, a further period is added and the forecasts in between are updated. The twelve-month view rolls the same way once a month, as described in our guide to moving from an annual budget to a rolling cash forecast.
A Worked Example: One Week, Three Changes
The figures below are invented to show the mechanics. The business, the customer and the amounts are illustrative.
A business of 35 staff on one ledger builds its forecast on Monday 26 October 2026 with £118,000 in the bank and a cash floor of £70,000, the balance below which it does not trade without a decision. Net pay leaves on the 25th and PAYE and National Insurance on the 22nd, each moved to the Friday before at a weekend. The VAT payment for the quarter to 30 September, £98,000, is already in the forecast on Friday 6 November, its bank date. The supplier run is the last working day of the month.
During the week, three things happen. A customer says its £48,000 invoice due on Friday 30 October will be paid on Friday 20 November, three weeks late. A hire due to start on 2 November is moved to 1 December, which takes £5,400 of net pay out of the November payroll. The VAT payment needs nothing: it was entered on its bank date when the return was filed. The finance manager moves the expected date on the invoice, re-dates the hire's budgets, and reads the forecast again.
| Week ending | What is in the week | Closing cash, before | Closing cash, after |
|---|---|---|---|
| 30 October | Receipts £131,000, including the £48,000 invoice; supplier run £41,000 | £208,000 | £160,000 |
| 6 November | Receipts £24,000; VAT £98,000 | £134,000 | £86,000 |
| 13 November | Receipts £31,000; payments £19,000 | £146,000 | £98,000 |
| 20 November | Receipts £27,000, plus the £48,000 after the move; PAYE and NI £44,000 | £129,000 | £129,000 |
| 27 November | Receipts £84,000; net pay £107,400 before the hire moves, £102,000 after | £105,600 | £111,000 |
| 4 December | Receipts £41,000; supplier run £41,000; other payments £14,000 | £91,600 | £97,000 |
Before the changes, the low point is the week ending 4 December, at £91,600, which clears the floor by £21,600. After the changes, the low point is the week ending 6 November, at £86,000, which clears the floor by £16,000. The tight week has moved four weeks closer and sits on the VAT payment.
Two things are worth reading off the table. The hire moving to December adds £5,400 to every week from 27 November and does nothing for the week that is now tight, because the VAT leaves three weeks before the hire would have been paid. And with £16,000 of headroom in the week ending 6 November, a second customer paying £16,000 late in that fortnight takes the business through its floor. The review's question for the finance director is one line: ask the customer for a part payment before 6 November, or hold part of the 30 October supplier run until the 20th. A month-end rebuild would have shown the same picture on 1 November, five days before the VAT leaves. The weekly updates showed it on 26 October, eleven days before, with the supplier run still to be decided.
How Float Keeps The Forecast Current
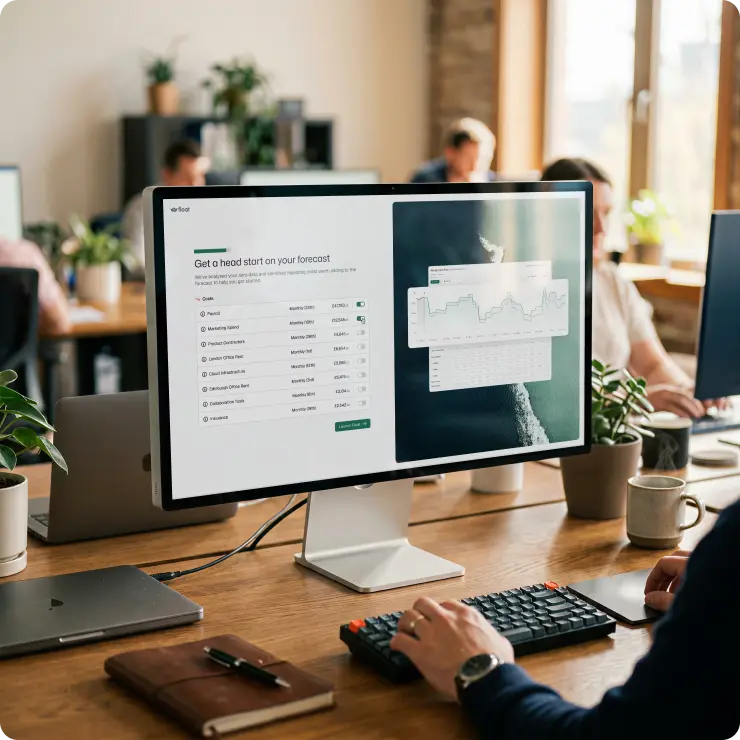
Float is cash flow forecasting software for in-house finance teams. It builds a 13-week weekly cash forecast on your accounting ledger, holds the group's companies, bank accounts and currencies in one view, and is built around the weekly routine above, so that much of the updating happens without anyone touching the forecast and the team's week goes on the lines that need a decision. Float connects to Xero and QuickBooks Online today, with Sage Intacct coming soon; you can join the Sage Intacct waitlist.
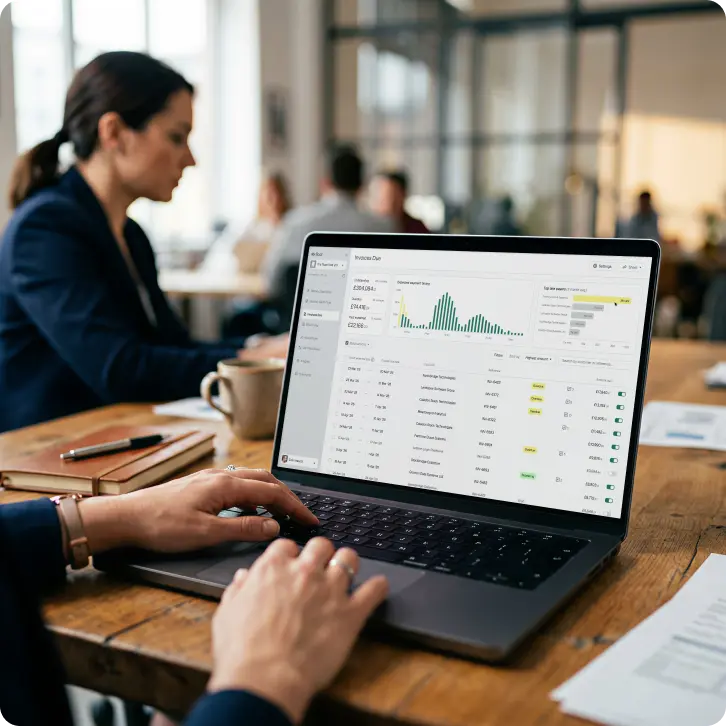
Actuals replace estimates every day. Float syncs with your accounting ledger once a day at an hour you choose, and you can run a manual sync whenever you want the latest figures. Each sync brings in reconciled transactions, invoices and bills, and as they land they replace the budgets they were standing in for; by month-end every actual has replaced its budget. The sync runs one way: Float reads your ledger and never writes back to it. The starting balance is the reconciled ledger balance of the bank accounts you include.
Expected dates set from how customers actually pay. Smart Expected Dates works out how many days late each customer and supplier has paid over up to twelve months and applies that average to new invoices and bills as they arrive, so a habitually late customer's next invoice lands in the week it is likely to be paid. It runs on Xero-connected companies; on other connections the team sets expected dates by hand. Any expected date can be moved, one at a time or in a batch, and an invoice can be split into part payments. An overdue invoice with no expected date is treated as paid today and marked in the app, so it gets a decision rather than sitting unnoticed. A comment on the invoice records why a date moved.
Budgets that follow the business. Plan changes go in as budgets, and two kinds keep themselves up to date. An auto budget tracks last month's figure, or the three- or six-month average, and updates as each month closes. A linked budget follows another line as a percentage, with an optional delay, so commission paid 60 days after a sale moves when the sales budget moves. Float also suggests regular income and costs from your history, for you to accept or leave.
Decisions tested before they are made. A hire can be modelled in the People costs tab: you enter the details, Float calculates the employment costs, and you switch the hire on and off to see what it does to cash. Any other what-if goes into a scenario layer on top of the base forecast; a scenario changes budgets only, not invoices, bills or bank data. When the decision is made, its budgets move into the base.
One weekly review, one forecast. You set a threshold for the balance you do not want to fall below, and Float shows the date the forecast is due to cross it. It is a date on screen, not an alert. Four user roles, including a read-only viewer, mean the finance manager maintains the forecast and the finance director and chief executive read the same one. The forecast exports as a PDF or a CSV when you run the export.
What Changes For The Finance Team
The weekly rebuild goes. The forecast takes its actuals from the ledger every day and its expected dates from payment history, so the weekly review starts from the current position and the team spends its time on the handful of lines that changed. In the worked example, that is the difference between seeing the tight week eleven days ahead and five.
Plans hold as timing shifts. When a customer slips, the date moves and the new low point is on screen the same morning, with time to chase a receipt or hold a payment. Hiring decisions are tested before anyone signs a contract: the finance director sees what a November start does to the low point, and what moving it to December does. And the forecast stops depending on one person. The finance manager maintains it, the finance director and chief executive read the same version, and the reason for every moved date sits on the invoice.
What Still Needs A Person
The judgement stays with the team. Software can replace an estimate with an actual the day it lands, set an expected date from a customer's history and show where the balance falls. It cannot decide whether a customer's latest promise is credible, what to do about a tight week, or whether a hire should wait.
Three judgements come up every week. Whether to believe a promised date: a customer that has missed its last three promises has told you something its latest promise has not. What to do about a tight week: chase a receipt, move a payment, draw on a facility, or accept it. And when a possibility becomes a decision and moves from a scenario into the base.
Where This Is Going
A rolling cash forecast is not new. What is still done by hand is much of the checking around it, and that checking is the subject of this page. Float's view is that the forecast should become a cash system the team runs: one that keeps reconciling what was expected with what happened, reassesses what is likely to happen next, and shows where attention is needed. That depends on a richer record of how cash moves through a business, including when customers pay, when suppliers are paid, and how forecasts differ from actuals. Float sets one condition on that direction. The numbers have to stay traceable to their source and under the finance team's control.
Frequently Asked Questions
How do finance teams keep a cash forecast up to date as invoices are paid late and plans change, without rebuilding it each month?
By making four small updates each week instead of one rebuild each month. Actuals replace estimates as they land. Expected dates are moved when a payment slips, leaving the due date alone. Plan changes go in as budget changes on the dates they will hit cash. Then one weekly review reads what moved and where the low point now falls.
How often should a cash flow forecast be updated?
Weekly for the short-term view, with the four updates above, and monthly for the twelve-month view. ICAEW's guidance for uncertain conditions says cash meetings should be weekly at minimum, with frequency set by the level of concern; the Association of Corporate Treasurers describes operational forecasts as updated weekly or monthly. A forecast updated less often than the news arrives is a report.
Why is my cash flow forecast inaccurate within a week of being built?
Because its dates are expectations, and three things move them: customers paying after the due date, supplier and payroll costs leaving on different dates from the ones planned, and plans changing after the forecast was set. A short-term forecast is built from actual receivables and payables plus expected receipts and payments, and the uncertainty widens the further ahead it looks.
What is the difference between updating a cash forecast and rebuilding it?
A rebuild starts again from the ledger at a fixed interval and replaces the whole forecast. An update changes only the lines that moved, in the week they moved, and leaves the rest standing. Both arrive at the same forecast on the day of the rebuild. The difference is every other day, when one is current and the other is waiting.
Does cash flow forecasting software keep the forecast up to date automatically?
Much of it. Software connected to the ledger replaces estimates with actuals every day. In Float, Smart Expected Dates sets expected dates on new invoices from each customer's payment history for Xero-connected companies, and auto and linked budgets update with your history and the lines they follow. The judgement on promises, tight weeks and plan changes stays with the team.
Should a new hire go into the base forecast or a scenario?
It depends on whether the hire has been decided. A confirmed hire goes into the base forecast as budgets for net pay and employer costs on the dates they leave the bank. A hire under discussion is modelled separately, so its effect on the low point can be read against the base without changing it. Once decided, it moves into the base.
Float is built for in-house finance teams of three or more who run cash across several bank accounts, entities or currencies and need the forecast current every week, not just at month-end. If that is your team and your forecast is right on the day it is built and wrong by the following Monday, start a 14-day free trial of Float, no card required. Connect your ledger, and the invoices, bills and reconciled balances arrive on their own; the decisions stay yours.